Reid Agency does two things out of Fort Wayne. We help families get protection that actually fits, and we train the people who want to do this for a living. Pick the door that's yours.
You've got people depending on you and no real idea what would happen if your income stopped. Let's put a number on it and find out what it costs.
You want work where your effort shapes your future, that you can do from home, with real mentorship behind you. That's the job.
My job is to make sure you have the right protection in place, and that you understand every benefit available to you. You don't need to know which of these you need — that's what the first call is for.
Most families pay their debts in the order the debts arrived rather than the order that costs least. This looks at what you owe and what you already put toward it each month, and whether changing that order — with a cash-value life insurance policy doing part of the work — would clear it sooner. It depends entirely on your own numbers, and I’ll run yours in front of you before you decide anything.
Families carrying debtIndexed universal life can build cash value you may later access as policy loans rather than withdrawals, which is generally income-tax-free when the policy is funded and maintained properly. Loans and withdrawals reduce the cash value and the death benefit, and the growth is not guaranteed. Some families use the same structure to set money aside for a child’s college.
Already covered, looking aheadCoverage for the people who depend on your income, sized around replacing it, covering childcare, and keeping plans on track. Term for a window of years, whole life for permanence.
Parents & income earnersLife insurance sized to what you owe on your home, so your family can stay in it if something happens to you. Coverage can be set to the length of your mortgage, and many policies include living-benefit riders that may help if you become seriously ill.
HomeownersSmaller policies built to cover a funeral, burial, and the bills that follow, so the people you love aren’t making hard decisions with a credit card. Health questions only — often no exam.
Seniors & fixed incomesCoverage that may replace part of your paycheck if illness or injury keeps you from working, or pay a lump sum after a covered diagnosis such as cancer, heart attack, or stroke. Benefits, waiting periods, and exclusions vary by policy, so we’ll read the details together.
Income earners
Twenty minutes on the phone or by video. I ask what you're worried about and what's already in place.
I compare your options across the 19 carriers I work with and come back with them side by side, with the real monthly cost on each.
Pick one, pick none, or sit on it. If you move forward I handle the paperwork and stay your point of contact.
Most people guess low. Move the sliders for a rough number on your own situation. Nothing is sent anywhere, and you don't have to give me your name to use it.
Rough numbers are fine. We'll sharpen them if we talk.
That's roughly what it would take to clear your debts and keep your household running for 10 years.
This is a simplified estimate for discussion, not a quote, an application, or a recommendation. It assumes education at $75,000 per child and doesn't adjust for inflation, taxes, investment returns, or Social Security survivor benefits. Your actual need — and what any policy would cost — depends on underwriting and your full financial picture.
We’re all independent agents, but we work together as a team to research the best coverage for our clients, and what’s best for the client always comes first. If you want to shape your own future with your work ethic, drive, and ambition — and still have mentorship, training, and support — this could be the place for you.
Our virtual office lets you watch agents talk with clients and run appointments, with live coaching along the way. You’ll have scripts to work from and mentorship every step of the way.
We encourage agents to work several sources: your warm market, referrals, and social media, which is a must if you want to grow your impact. We also offer paid leads at a range of price points, all warm — people who asked for more information.
Not licensed yet? That’s normal. We help new agents get licensed and walk you through what it takes. Appointments happen by phone and video, so you can work from home and set your own schedule.


Watching an agent learn, grow, and blossom gives me such joy. Like James B., who came into this business from a career in construction. He stuck it out and did the work.
Karin Reid, Reid AgencyThis is a 1099 independent-contractor, commission-only role. There is no salary, and income depends entirely on your own production. Agents must hold or obtain a state life insurance license and cover their own business costs, such as licensing and any leads they choose to buy. Nothing here is a promise or projection of earnings.

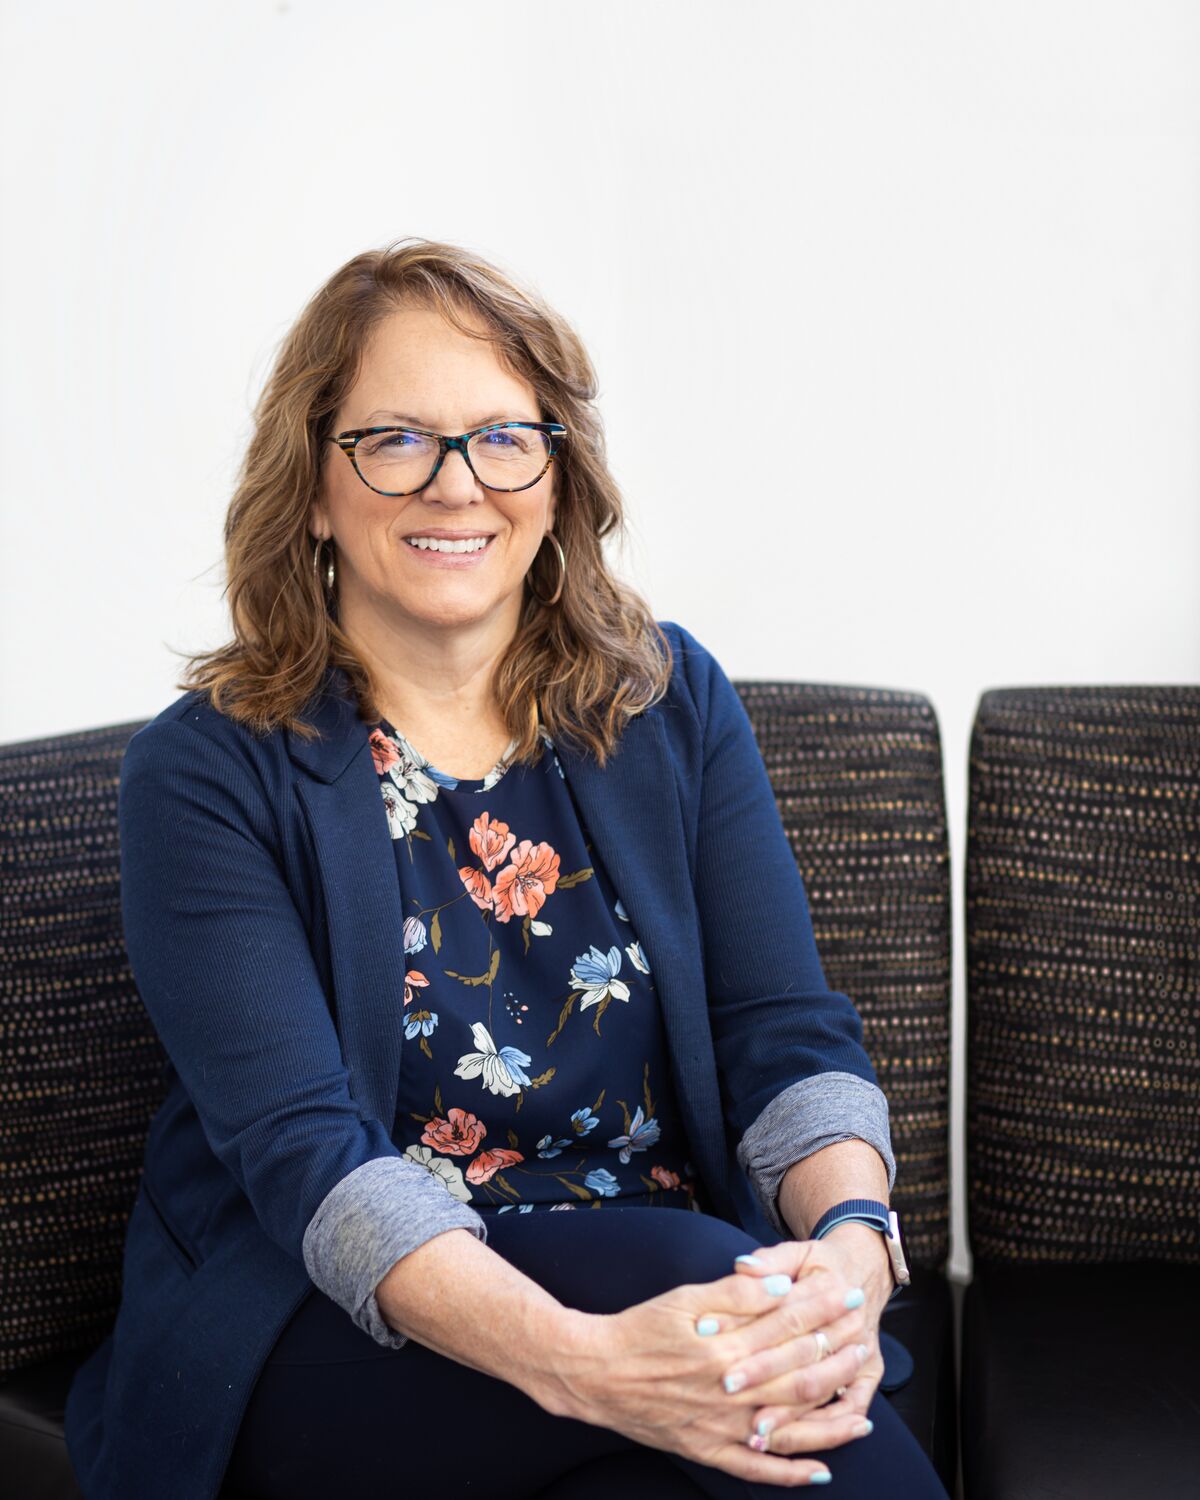
I never set out to be an insurance agent. I spent more than twenty years in direct sales, and when the company I was with closed abruptly in 2013 I took a job with a friend doing consulting work. Life insurance was something I stumbled into after that. I did not expect to love it. I do.
What I love is the first half of the conversation — the part where somebody tells me what they are actually worried about. Then I get to show them there is something they can do about it. After twenty years of selling things, that still feels like a different kind of work.
Early on I sat down with a husband and wife about protecting their home, so she would not lose it if he died. He was in his early sixties and healthy. Two months later she called to tell me he was gone — a virus the doctors could not treat, and then sepsis. She kept her home. She was deep in grief, and she did not have to worry about money on top of it. I felt privileged to have been the one who put that in place.
I was born in Indiana, though I have also lived in Pennsylvania, Colorado, and Ohio. We came to Fort Wayne in 1991, and I love this city — the people, the vibrance. It is the first time in my life I have felt rooted. The other half of my work now is training the people who want to do this job themselves.
My husband, Chuck, and I are grateful to have the blessing of protecting families.
Karin Reid, Reid AgencyLess than most people guess, and it depends on your age, health, the amount, and the type. A healthy thirty-five-year-old looking at term coverage is often surprised on the low side. The only honest answer is to run your numbers through a few carriers, which costs you nothing.
Often not. A lot of carriers now underwrite using health questions and prescription history instead of a paramedical exam, which means coverage can be approved in days rather than weeks. If your health history makes one carrier a poor fit, that's exactly the sort of thing being independent lets me work around.
Sometimes, and sometimes not. Group coverage is a real benefit, but it's usually a multiple of salary rather than a number tied to your actual obligations, and it typically ends when the job does. Bring your benefits summary and we'll look at it together.
Yes. Bring it in and I’ll read it with you and tell you plainly whether to keep it, adjust it, or shop it. Often the answer is keep it.
Through our network of agents we serve families in all 50 states. I’m personally licensed in 37: Alabama, Arizona, California, Colorado, Delaware, Florida, Georgia, Idaho, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana, Maine, Maryland, Massachusetts, Michigan, Mississippi, Missouri, Nebraska, Nevada, New Jersey, New Mexico, North Carolina, Ohio, Oklahoma, Pennsylvania, South Carolina, South Dakota, Tennessee, Texas, Utah, Virginia, Washington, West Virginia, and Wisconsin. Anywhere else, a licensed agent on our team writes the policy. Appointments happen by phone or video, so distance isn’t a problem.
No. We help new agents get licensed. It means a pre-licensing course, a state exam, and a background check, and we’ll walk you through each step. Plenty of people on this path started from zero.
No. It's a 1099 independent-contractor role paid on commission, which means there's no ceiling and no floor. That suits some people and genuinely doesn't suit others, and I'd rather be straight with you about it up front than have you find out in month three.
No. You'll get the numbers you asked for, and then it's your move. If you'd rather I check back in six months, say so and I will. Otherwise I'll leave you alone.
Whichever door you came in through. Tell me a little and I’ll come back to you — no obligation either way. Or pick a time on my calendar and skip the form.
One conversation. If it turns out you don't need anything from me, I'll tell you that too.
What I'm sharing